A new Colorado law took effect July 1 that changes how insurers treat the work you do to protect your home from wildfire. If you’ve hardened your home or cleared the area around it, the Colorado wildfire mitigation insurance discount rules give you a way to ask for credit at renewal. That matters for anyone planning outdoor living spaces right up against the house.
Quick Answer: How the Colorado Wildfire Mitigation Insurance Discount Works
Under HB25-1182, insurers that use wildfire risk models must either build mitigation into the model or give a discount to homeowners who can show the work. You can ask for a revised risk score after the work is done, and you can appeal a score you think is wrong. Don’t expect much money: a state study averaged wildfire mitigation savings at $3 to $25 a year in the counties it looked at. The real value is a lower risk to your home and a paper trail your insurer has to consider.
What HB25-1182 Changed on July 1
Governor Polis signed HB25-1182 in May 2025, and it applies to property policies issued or renewed on or after July 1, 2026. It covers homeowners policies statewide, including the Colorado FAIR Plan. Per the signed act, most homeowners will see the changes at their next renewal. Insurers now have to:
- Factor in property-level mitigation such as defensible space and building hardening
- Post their available discounts and their appeal process on their public websites
- Give you a revised wildfire risk score within 30 days of your request, for mitigation done since your last application or renewal
- Acknowledge a written appeal within 10 calendar days
The clearest proof the law names is a Wildfire Prepared Home designation from the Insurance Institute for Business and Home Safety, or a similar program with verification. That program is available in Colorado. Some insurers may also credit individual steps, so check what yours lists.
Home Upgrades That Count Toward a Wildfire Mitigation Discount
The work that matters most sits closest to the house. A property breaks into three zones, per the Colorado State Forest Service, and Zone 1 is the first five feet. Zone 2 runs from 5 to 30 feet, where fuels should be thinned, and Zone 3 reaches out to 100 feet.
Zone 1: The First Five Feet
Flying embers are the most common way homes ignite, and they can light mulch and shrubs at the base of the house. CSFS home-hardening steps include:
- Screening attic, roof, eave, and foundation vents with 1/8-inch metal mesh
- Replacing combustible fencing or gates, at least within 5 feet of the home
- Treating any fence attached to the house as part of the structure
That’s where design choices on a patio or hardscape project come in. A noncombustible surface along the foundation does the job a strip of bark mulch can’t.
Decks and the Space Under Them
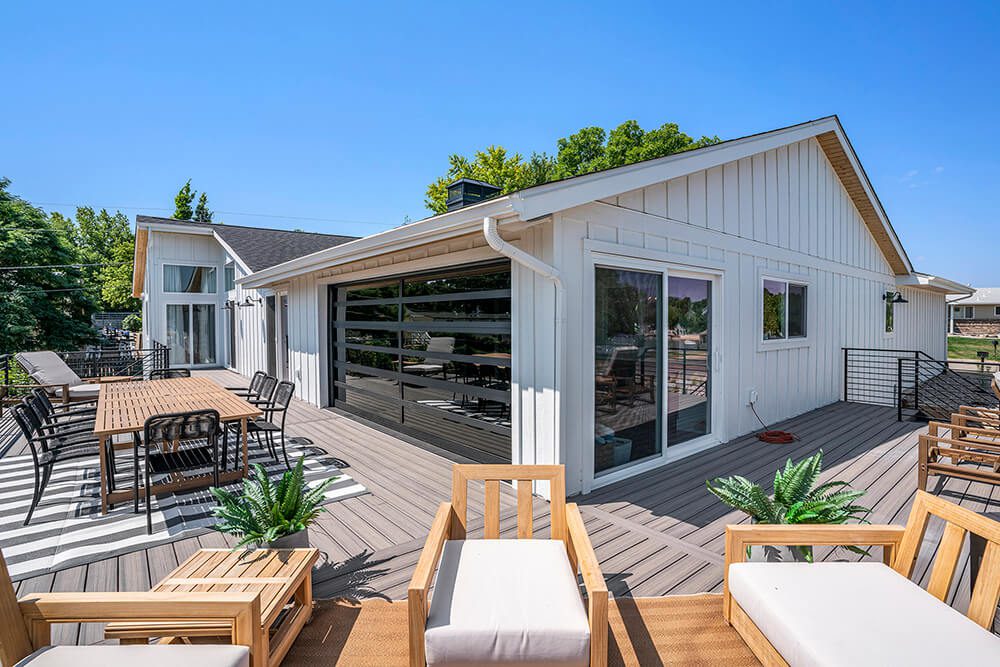
Decks catch embers. CSFS notes that many deck designs let embers collect between the boards, and it says not to use the space under a deck for storage. The state’s wildfire preparedness guide also recommends building fire-resistant decks and enclosing low decks.
How to Ask Your Insurer for a Revised Wildfire Score
The law gives you a process, and it runs on deadlines. Here’s the order that makes sense:
- Check your insurer’s website for its wildfire discounts and appeal process, since the law requires insurers to post both.
- Finish the work and document it with dated photos, invoices, and any certification.
- Request a revised score. The insurer has 30 days after your request to provide it.
- Appeal if it still looks wrong. The insurer must acknowledge in writing within 10 calendar days and decide within 30.
Final Thoughts on the Colorado Wildfire Mitigation Insurance Discount
The Colorado wildfire mitigation insurance discount won’t pay for a project on its own. What it does is make your insurer consider the work, publish its discounts, and answer your appeal by a deadline. Do the work in the first five feet, take photos, keep the invoices, and ask for a revised score once it’s finished.
If you’re planning a patio or outdoor living space this year, it’s a good time to think about those details. Contact us for a free, no-obligation quote.